What Happens to Your Car in Chapter 7 Bankruptcy
Filing for bankruptcy? Find out what happens to your car in Chapter 7 bankruptcy and how to protect it. Call (833)-349-4659 for a free case review.
By Orion Fletcher
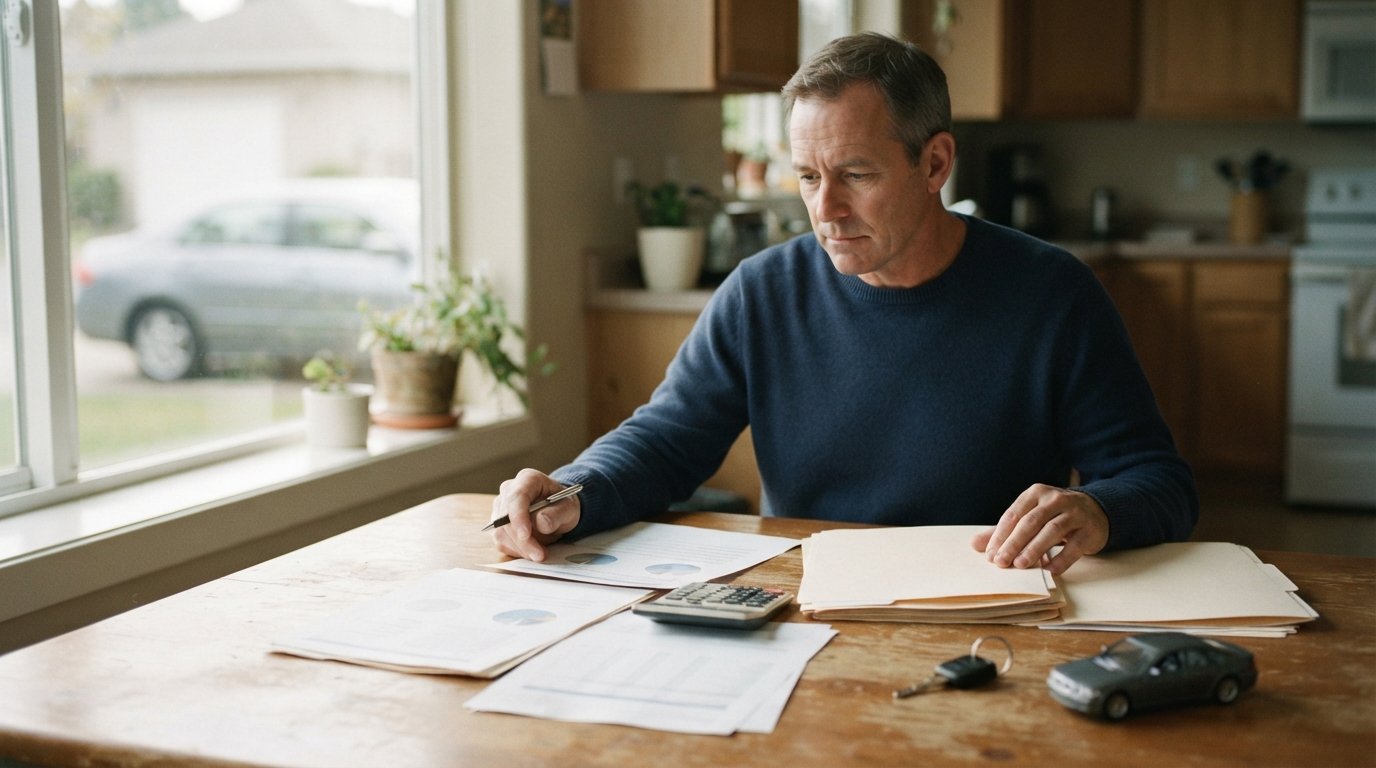
Facing Chapter 7 bankruptcy often brings a wave of anxiety, and one of the most pressing concerns is what will happen to your car. You rely on your vehicle for work, family, and daily life, so the fear of losing it is understandable. The good news is that in many cases, you can keep your car, but the outcome depends on several factors including state exemption laws, your equity in the vehicle, and whether you have a loan. This article explains what happens to your car in Chapter 7 bankruptcy, covering exemption amounts, your options for reaffirmation, redemption, or reinstatement, how equity is calculated, lienholder rights, and steps to plan before filing. By understanding these rules, you can make informed decisions to protect your vehicle.
Understanding Chapter 7 Bankruptcy and Your Car
Chapter 7 bankruptcy, often called liquidation bankruptcy, involves a court-appointed trustee who sells your non-exempt assets to pay creditors. However, exemptions allow you to protect certain property, including a vehicle up to a specific value. The trustee will evaluate your car's equity, which is the difference between its market value and any outstanding loan balance. If your equity falls within the exemption limit, you can keep the car. If it exceeds the limit, the trustee may sell the car, pay you the exempt amount, and distribute the remainder to creditors. The process is governed by federal and state exemption laws, and most states allow you to choose between federal and state exemptions, though some states require you to use state exemptions only.
It's important to note that filing for bankruptcy triggers an automatic stay, which halts collection actions, including repossession. This protection gives you breathing room to decide how to handle your car. However, the stay does not eliminate your obligation to pay for the car if you want to keep it. If you are behind on payments, the lender may seek relief from the stay to repossess the vehicle unless you make arrangements. Understanding these basics sets the stage for exploring your options.
State Exemption Amounts and Motor Vehicle Allowances
Each state has its own exemption laws that determine how much equity you can protect in a vehicle. Some states offer a wildcard exemption that can be applied to any property, including a car, while others have a specific motor vehicle exemption. For example, California offers a vehicle exemption of up to $7,500 for a single filer, while Texas allows unlimited equity in one vehicle per adult. Other states like Florida also have generous vehicle exemptions. The federal bankruptcy exemptions, available in some states, include a $4,000 motor vehicle exemption (as of 2025, subject to adjustment). It's crucial to check your state's specific exemption amounts and whether you can use federal exemptions.
If you are married and filing jointly, you may be able to double the exemption amount if you both have ownership interest in the car. Some states also allow a wildcard exemption to cover any unused amount. Understanding these allowances helps you determine if your car is safe. For instance, if your car is worth $10,000 and you have a $5,000 loan, your equity is $5,000. If your state's vehicle exemption is $7,500, you can protect the entire equity and keep the car. However, if your equity exceeds the exemption, the trustee may sell the car and give you the exempt amount. Planning ahead by knowing your state's rules is essential.
Your Options: Reaffirmation, Redemption, and Reinstatement
If you have a car loan, you have several options to keep your vehicle in Chapter 7 bankruptcy. The most common are reaffirmation, redemption, and reinstatement. Each has different implications for your finances and credit.
Reaffirmation
Reaffirmation means you agree to remain personally liable for the car loan, essentially reaffirming the debt. This option allows you to keep the car and continue making payments. However, it requires court approval and must be in your best interest. Reaffirming a debt means you cannot discharge it in bankruptcy, so if you later fall behind, the lender can repossess and sue for the deficiency. It's important to carefully consider whether the car is worth the debt and if you can afford the payments.
Redemption
Redemption allows you to pay the lender the current fair market value of the car in a lump sum, typically within a certain period after filing. This option is useful if you owe more than the car is worth. For example, if you owe $10,000 but the car is worth $6,000, you can pay $6,000 to own the car free and clear. However, you need to come up with the lump sum, which may be difficult. Some lenders may offer financing for redemption, but terms vary.
Reinstatement
Reinstatement involves catching up on missed payments to bring the loan current. This option is available if you are behind but can pay the arrears. Once reinstated, you continue making regular payments. Reinstatement does not require court approval and does not reaffirm the debt, so the loan remains dischargeable in the future if needed. However, you must act quickly before the lender obtains relief from the automatic stay.
Each option has pros and cons. Reaffirmation keeps the car but ties you to the debt; redemption frees you from the loan but requires cash; reinstatement gets you back on track but requires catching up. Consult with a bankruptcy attorney to determine the best choice for your situation.
How Equity in a Car Is Calculated
Equity is the key factor in determining whether you can keep your car in Chapter 7 bankruptcy. It is calculated by subtracting the outstanding loan balance from the car's current market value. For example, if your car is worth $12,000 and you owe $8,000, your equity is $4,000. If you own the car outright, your equity equals its value. The trustee will use resources like Kelley Blue Book or NADA to determine value, but you can provide your own appraisal if you disagree.
If your equity is within the exemption limit, you can keep the car. If it exceeds the limit, the trustee may sell the car, pay you the exempt amount, and use the rest to pay creditors. However, if there is a lien on the car, the trustee must pay the lienholder first. In many cases, cars with loans have little or no equity, making them safe from liquidation. It's important to accurately value your car and know your state's exemption to avoid surprises.
Lienholders and Repossession Rules During Bankruptcy
The automatic stay prohibits creditors from repossessing your car after you file for bankruptcy. However, lienholders can request relief from the stay if they believe their interest is not adequately protected. For example, if you are not making payments and the car is depreciating, the lender may argue that its collateral is at risk. If the court grants relief, the lender can repossess the car. To prevent this, you must stay current on payments or make other arrangements.
If you have a loan and want to keep the car, you must continue making payments. If you are behind, you can propose a plan to catch up, but Chapter 7 does not allow for a repayment plan like Chapter 13. Therefore, you may need to negotiate with the lender or consider redemption. If you surrender the car, the lender can sell it and may seek a deficiency judgment if the sale proceeds are less than the loan balance. However, in Chapter 7, any deficiency is typically discharged, meaning you are not personally liable. It's crucial to communicate with your lender and understand your rights.
Steps to Plan Vehicle Ownership Before Filing
Planning ahead can help you protect your car in Chapter 7 bankruptcy. Here are steps to consider:
- Determine your equity: Calculate your car's market value and subtract the loan balance. Compare this to your state's exemption amount.
- Review exemption options: Check if your state allows federal exemptions or has a wildcard exemption you can apply.
- Consider timing: If you are expecting a tax refund or bonus, time your filing to maximize exemptions or pay down your loan.
- Communicate with your lender: Discuss your options for reaffirmation, redemption, or reinstatement before filing.
- Consult a bankruptcy attorney: An attorney can help you navigate the complexities and make informed decisions.
Additionally, avoid transferring ownership of your car to someone else before filing, as this could be seen as fraudulent and lead to denial of discharge. Also, do not take on new debt to pay off the car, as this could complicate your bankruptcy. Proper planning ensures you keep your car if possible and avoid legal pitfalls.
When to Seek Legal Guidance
Bankruptcy laws are complex and vary by state. If you are unsure about your car's fate, it's wise to consult a bankruptcy attorney. They can help you understand exemptions, evaluate your options, and represent you in court. If you need help finding a qualified attorney, consider using a platform like FormsByLawyers, which connects you with top-rated attorneys through a patented selection process. For more information on how legal representation can maximize your outcomes, read our guide on how a car accident injury attorney maximizes your settlement, which offers insights into attorney value. Additionally, resources like AttorneyLawsuit provide valuable information on legal disputes and consumer rights.
Remember, bankruptcy is a serious decision, and having professional guidance can make a significant difference. Whether you are trying to keep your car or surrender it, an attorney can help you navigate the process and protect your rights.
In summary, what happens to your car in Chapter 7 bankruptcy depends on your equity, exemptions, and loan status. By understanding the rules and planning ahead, you can make the best choice for your situation. If you need assistance, reach out to a bankruptcy attorney or use a trusted legal resource to connect with one.