Signs You Should Consider Filing for Bankruptcy
Recognizing the signs you should consider filing for bankruptcy can help you decide when to seek legal relief and start rebuilding your finances.
By Milo Calderon
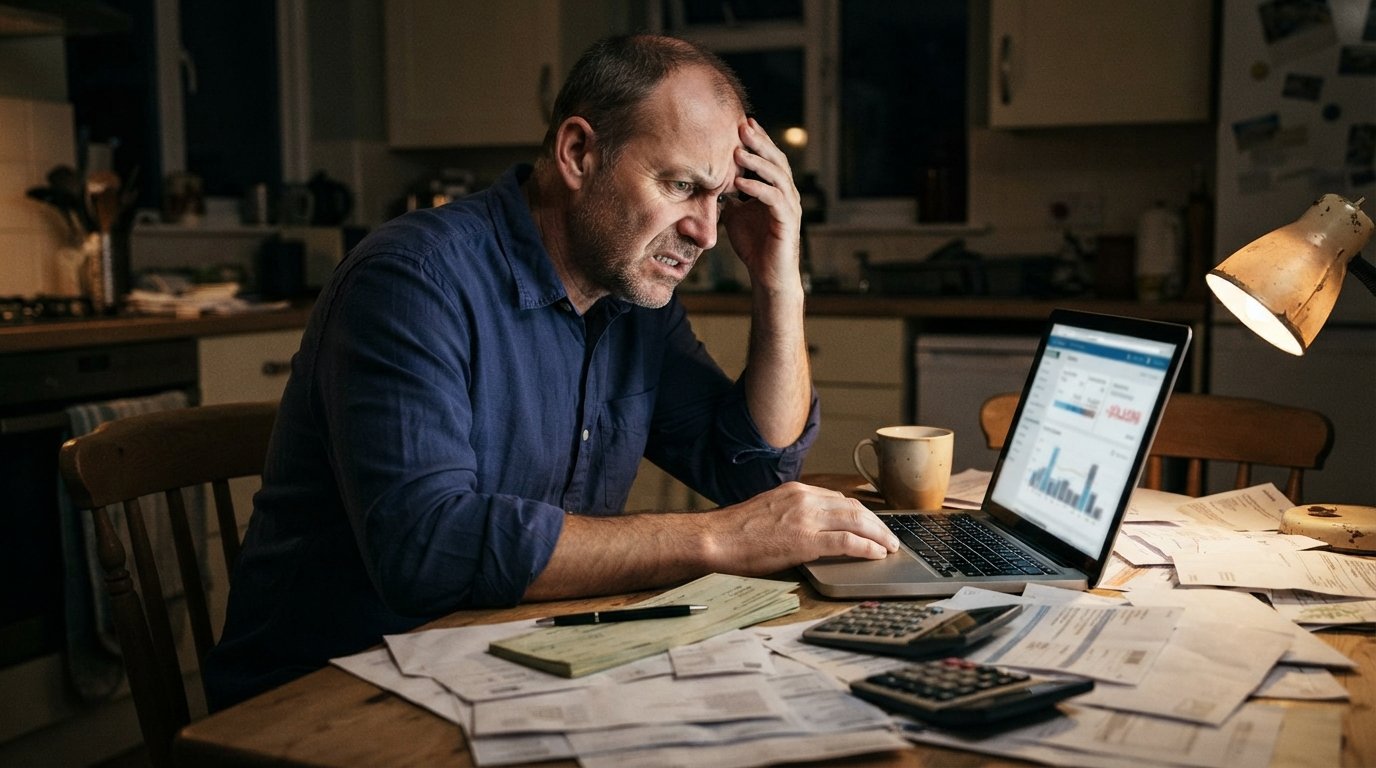
Financial pressure rarely announces itself with a single dramatic moment. More often, it builds quietly through missed payments, growing balances, and a sinking feeling that no matter how hard you work, the math simply will not cooperate. If you have started avoiding phone calls from creditors, lying awake at night doing mental calculations, or wondering whether your paycheck will stretch far enough to cover the essentials, you are not alone. Millions of Americans face this exact crossroads every year. The question is not whether you are struggling, but whether bankruptcy is the right tool to help you climb out of it. Understanding the signs you should consider filing for bankruptcy can transform a vague, frightening possibility into a clear, actionable decision.
Bankruptcy carries a stigma that often prevents people from seeking help until their situation becomes truly desperate. In reality, bankruptcy laws exist precisely to give honest people a fresh start when debt becomes unmanageable. It is a legal protection, not a moral failing. The key is recognizing when your financial situation has moved beyond temporary difficulty and into territory where bankruptcy could provide meaningful relief. This article walks through the most reliable warning signs, explains what each one means, and helps you understand when it might be time to speak with a legal professional about your options.
Your Debt Is Growing Faster Than Your Ability to Pay
One of the earliest and most telling signs that bankruptcy might be worth considering is when your total debt continues to climb even as you make payments. This happens when interest rates, late fees, and penalty charges outpace whatever you can afford to send each month. You might be paying the minimum on credit cards, only to watch the balance creep upward. You might be juggling multiple loans, robbing Peter to pay Paul, and finding that the overall picture never improves.
This pattern is a clear indicator that your current strategy is not working. When you are paying what you can but still falling further behind, the problem is structural, not motivational. No amount of budgeting or side hustling will solve a debt load that generates more in interest than you can realistically earn to pay it down. At that point, you are essentially running on a treadmill that speeds up every time you try to catch your breath.
Consider this scenario: You owe $30,000 across several credit cards with an average interest rate of 22 percent. If you can only afford $600 per month, you are barely covering the interest, and the principal never meaningfully decreases. After five years of faithful payments, you might still owe nearly the same amount. This is the kind of mathematical trap that bankruptcy is designed to address.
You Are Using Credit to Cover Basic Living Expenses
There is a significant difference between using credit for convenience and using credit for survival. When you start charging groceries, utilities, or gas because your bank account is empty, you have crossed into dangerous territory. This sign often signals that your income simply does not cover your essential expenses, let alone your debt obligations. It is a clear indication that your financial foundation is cracking.
Using credit cards to buy food or pay for electricity means you are borrowing money to live. Each month, the balance grows, and the interest compounds. Eventually, you may max out every available card and still find yourself short. This is not a budgeting problem you can solve by clipping coupons. It is a sign that your debt-to-income ratio has become unsustainable and that you need a more powerful solution.
When you reach this point, you may also notice that you are paying for necessities with money that was supposed to go toward debt payments. You might skip a credit card payment to keep the lights on, then face late fees and a higher interest rate. This cycle accelerates quickly and can feel impossible to escape without intervention.
Creditors Are Calling, Suing, or Garnishing Your Wages
When creditors escalate their collection efforts, it is a strong signal that your situation has moved into a new phase. Persistent phone calls, threatening letters, and legal action are not just annoying; they are signs that your creditors are preparing to take more aggressive steps. If you have been served with a lawsuit or received notice of a wage garnishment, you are already in the crosshairs of the legal system.
A wage garnishment can take a significant portion of your paycheck before you ever see it, leaving you even less able to cover your bills. Bank levies can freeze your accounts, making it impossible to pay rent or buy food. These actions can snowball, and once they start, they are difficult to stop without legal protection. Bankruptcy can halt garnishments, lawsuits, and collection calls almost immediately through the automatic stay, giving you breathing room to reassess.
It is important to understand that ignoring these threats will not make them go away. Creditors have years of experience pursuing debts, and they will use every tool available. If you are facing legal action, speaking with a legal professional about your options becomes urgent.
You Have Experienced a Major Financial Shock
Life events such as job loss, a serious medical emergency, a divorce, or the death of a family member can devastate even the most carefully managed finances. These shocks often come with a double whammy: a sudden drop in income and a spike in expenses. When you are dealing with a health crisis or the emotional toll of a divorce, the last thing you need is the added pressure of overwhelming debt.
If a single event has left you with medical bills you cannot pay, a mortgage you can no longer afford, or credit card debt you accumulated just to survive, bankruptcy may be a reasonable path forward. It is designed to address exactly these kinds of situations, where circumstances beyond your control have made it impossible to meet your obligations.
For example, a person diagnosed with cancer might face tens of thousands of dollars in medical bills while also being unable to work. Even with insurance, out-of-pocket costs can be crippling. Bankruptcy can discharge those medical debts, allowing the person to focus on recovery rather than financial ruin.
Your Attempts to Negotiate or Consolidate Have Failed
Many people try to resolve their debt problems through negotiation, credit counseling, or debt consolidation loans before considering bankruptcy. These can be viable options for some, but they are not universally successful. If you have already tried to work with creditors, enrolled in a debt management plan, or taken out a consolidation loan, and you are still struggling, that is a sign that your situation may require a more definitive solution.
Debt settlement companies often promise to reduce your balances but may charge high fees and leave you in a worse position. Consolidation loans can lower your monthly payment, but they often extend the repayment period and can be difficult to qualify for if your credit is already damaged. If these avenues have failed, you may be throwing good money after bad.
Bankruptcy offers a legally binding resolution. Instead of hoping creditors will cooperate, you get a court-supervised process that can eliminate or restructure your debts. It is not a quick fix, but it is a reliable one.
You Are Considering Bankruptcy as a Tool for a Fresh Start
Perhaps the most important sign is a shift in mindset. If you have moved past the shame and fear and are now thinking about bankruptcy as a strategic tool to rebuild your financial life, you are likely ready to explore it seriously. Bankruptcy is not about giving up; it is about making a deliberate choice to address a problem that has become unmanageable.
Many successful people have used bankruptcy to reset their finances and go on to achieve financial stability. The law exists to provide a fresh start, and using it wisely is a sign of maturity, not failure. If you are researching how bankruptcy works, what chapter might be right for you, and how it could improve your situation, you are already on the right track.
It is also worth noting that bankruptcy can be a responsible choice when you have exhausted all other options. It can stop the bleeding, protect your assets, and give you a chance to rebuild. For those dealing with both financial hardship and legal challenges, such as a car accident, resources like CarInjuryAccident can provide guidance on multiple legal fronts, connecting you with attorneys who handle personal injury, bankruptcy, and other matters.
When to Seek Professional Guidance
Recognizing the signs is the first step. The next is to speak with a qualified attorney who can evaluate your specific circumstances. Bankruptcy laws are complex, and the right choice depends on your income, assets, types of debt, and long-term goals. A lawyer can help you determine whether Chapter 7 or Chapter 13 is more appropriate, explain the implications for your credit and property, and guide you through the process.
If you are unsure where to start, consider using a platform that connects you with experienced legal professionals. For example, our guide on No Win No Fee Injury Lawyers: Your Guide to Risk-Free Claims explains how to find representation without upfront costs, a model that can apply to some bankruptcy services as well. The key is to take action before your situation worsens.
Here are some practical steps to take if you recognize yourself in the signs above:
- Gather all your financial documents, including bills, bank statements, and pay stubs, to get a clear picture of your debt and income.
- Make a list of your debts, noting balances, interest rates, and whether they are secured or unsecured.
- Research the difference between Chapter 7 and Chapter 13 bankruptcy to understand which might fit your situation.
- Contact a reputable bankruptcy attorney or a legal resource platform to schedule a consultation.
- Be honest about your finances and your goals so your attorney can provide accurate advice.
Taking these steps can help you move from overwhelm to action. Remember that you do not have to navigate this alone, and there is no shame in seeking help.
Facing financial hardship is stressful, but it is also a situation that millions have successfully overcome. By paying attention to the warning signs and seeking professional guidance, you can make an informed decision about whether bankruptcy is the right path for you. The goal is not just to survive your current crisis, but to build a stable financial future.