How to Prepare Financially Before Filing for Divorce
Gather financial documents, build an emergency fund, and understand marital property rules to protect your money and avoid surprise bills before filing for divorce.
By Amaris Cole
Divorce is rarely just an emotional event. It is also a financial earthquake that can reshape your budget, your credit, your retirement, and your long-term stability. According to the American Psychological Association, money disputes are among the top predictors of divorce, and the financial aftershocks often linger long after the paperwork is signed. If you are considering ending your marriage, the steps you take in the weeks and months before you file can protect you from costly mistakes, reduce conflict, and give you a clearer picture of what life after divorce will actually look like. This guide explains how to prepare financially before filing for divorce so you can move forward with confidence instead of confusion.
Start With a Complete Picture of Your Finances
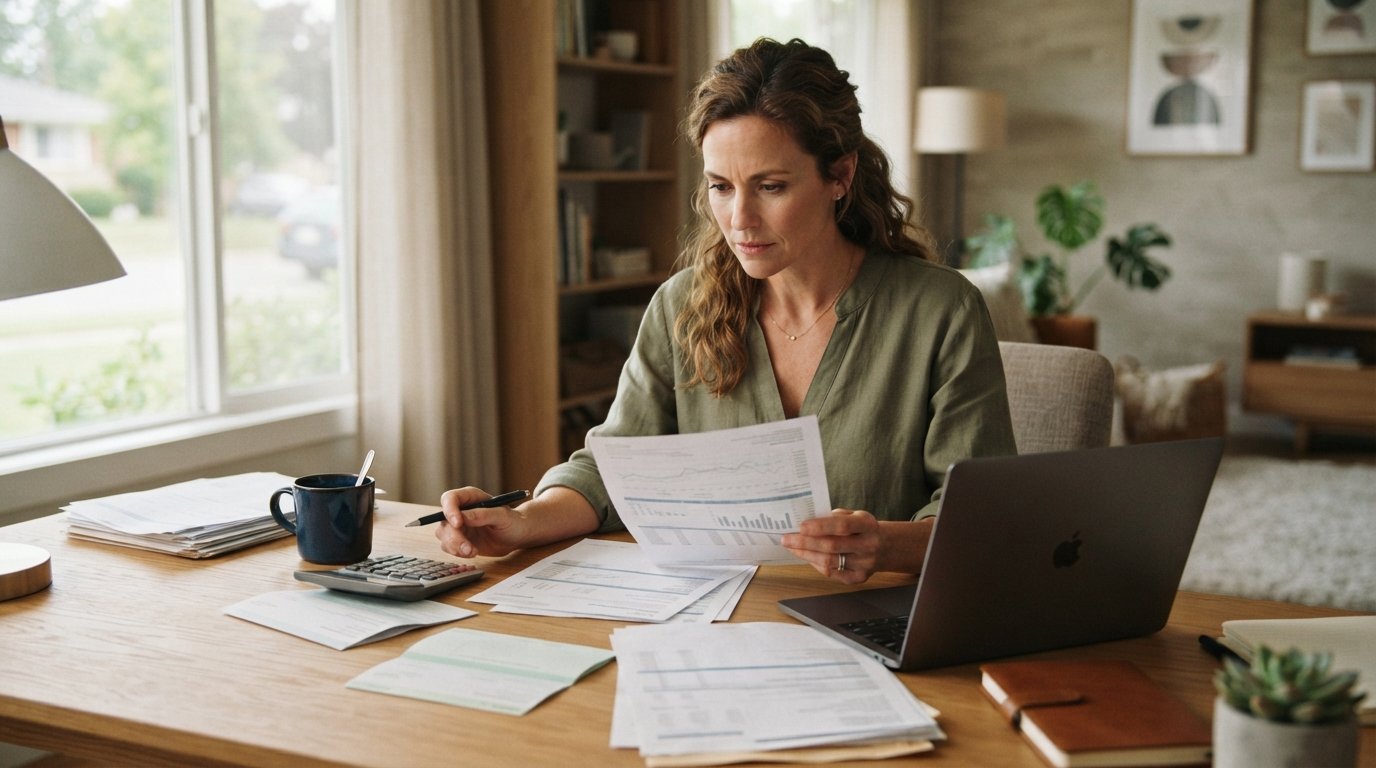
You cannot protect what you do not understand. Before you meet with an attorney or make any major decisions, gather a full inventory of your household finances. This includes every account, debt, asset, and recurring expense, even the ones your spouse has traditionally handled. Many people discover hidden accounts, forgotten retirement plans, or business interests only after a divorce is underway, and that delay can weaken their negotiating position.
Pull recent statements for all bank accounts, brokerage accounts, retirement plans, credit cards, mortgages, auto loans, and student loans. Request a free credit report from each of the three major bureaus to catch any accounts you may have forgotten. If you own a business or have an ownership stake in one, gather profit and loss statements, tax returns, and valuation documents. If you are not sure where to start, a family law attorney can help you identify the documents that matter most in your jurisdiction.
Once you have the raw data, organize it into categories. A simple spreadsheet works well:
- Assets: checking and savings accounts, retirement accounts, investment accounts, real estate, vehicles, business interests, valuable personal property
- Debts: mortgages, home equity loans, credit card balances, auto loans, student loans, medical debt, personal loans
- Income: salaries, bonuses, commissions, rental income, dividends, side business revenue, government benefits
- Recurring expenses: housing, utilities, insurance premiums, childcare, tuition, subscriptions, loan payments
This inventory becomes the foundation for every conversation you have with your attorney, your financial advisor, and your spouse. It also helps you spot red flags, such as accounts that have been drained, debts that appeared recently, or income that does not match the lifestyle you have been living. If you suspect your spouse is hiding assets or preparing for a divorce without telling you, document what you find and share it with your lawyer early.
Build Your Own Emergency Fund and Separate Credit
One of the most practical steps you can take is to establish financial independence before the divorce process begins. Open a bank account in your name only, at a different institution than the one you share with your spouse, and begin directing a portion of your income into it. Even a modest cushion of one to three months of essential expenses can prevent you from making desperate decisions later, such as accepting a poor settlement because you cannot afford to wait.
At the same time, apply for a credit card in your own name if you do not already have one. Building a separate credit history is important because joint accounts will eventually be closed or divided, and you do not want to be left without access to credit. Use the card lightly and pay it off monthly to establish a positive payment history. Avoid making large purchases or opening multiple new accounts at once, since that can hurt your credit score and raise questions during the divorce.
Do not close joint accounts or remove your spouse from existing accounts without legal advice. In many jurisdictions, doing so can be considered a violation of temporary restraining orders or automatic financial injunctions that take effect when a divorce is filed. Instead, focus on building your own resources while leaving shared accounts intact until your attorney tells you otherwise. If you are concerned about your spouse draining a joint account, ask your lawyer about a protective order or a mutual agreement to freeze spending.
Understand What Is Marital and What Is Separate Property
Divorce law varies by state, but most jurisdictions distinguish between marital property and separate property. Marital property generally includes assets and debts acquired during the marriage, regardless of whose name is on the account. Separate property typically includes assets owned before the marriage, inheritances, and certain personal injury awards. Understanding this distinction is critical because it determines what you may be entitled to and what you may be required to share.
If you live in a community property state, such as California, Texas, or Arizona, most property acquired during the marriage is owned equally by both spouses. In equitable distribution states, courts divide marital property fairly but not necessarily equally, considering factors like the length of the marriage, each spouse's earning capacity, and contributions to the household. An attorney licensed in your state can explain how these rules apply to your situation and help you identify any assets that should be classified as separate.
This is also the time to think about retirement accounts, pensions, and stock options. These assets are often the largest part of a divorce settlement, and dividing them incorrectly can trigger taxes and penalties. A qualified domestic relations order, or QDRO, is typically required to divide employer-sponsored retirement plans without penalties. If your spouse has a pension or deferred compensation, ask your attorney how to value and divide it properly.
Review Your Insurance Coverage and Beneficiary Designations
Insurance is one of the most overlooked areas of divorce planning. Before you file, review your health insurance, life insurance, auto insurance, homeowners or renters insurance, and disability coverage. Determine whether you will lose coverage when the divorce is finalized and what it will cost to obtain your own policy. If you have children, confirm that they will remain covered under a plan that works for both households.
Update your beneficiary designations on retirement accounts, life insurance policies, and payable-on-death accounts. In many cases, a divorce decree does not automatically override a beneficiary designation, so an ex-spouse could still inherit your assets if you forget to update the paperwork. At the same time, do not make changes that violate a court order or a separation agreement. Ask your attorney to review your plans before you submit any forms.
If you rely on your spouse's health insurance, research options through your employer, the Affordable Care Act marketplace, or a private plan. A temporary continuation of coverage may be available through COBRA, but it is often expensive. Knowing your options ahead of time prevents gaps in coverage and helps you budget accurately for post-divorce life.
Plan for Taxes and Cash Flow After Divorce
Divorce changes your tax situation in ways that are easy to underestimate. Filing status, deductions, credits, and the tax treatment of alimony and child support all depend on the terms of your settlement and the year the divorce is finalized. For example, alimony is no longer deductible for the payer or taxable for the recipient under federal law for divorces finalized after 2018, but state rules may differ. Child support is generally not deductible or taxable.
Work with a tax professional to model your post-divorce tax liability. If you will be receiving the family home, you may face property tax reassessment, maintenance costs, and capital gains implications when you eventually sell. If you will be paying support, you need to know how much you can realistically afford while still meeting your own obligations. Cash flow projections should include housing, utilities, transportation, childcare, health insurance, and debt payments.
If you are facing overwhelming debt alongside divorce, you may also want to explore whether bankruptcy is a better path. Bankruptcy and divorce can interact in complex ways, and the order in which you file can affect what debts are discharged and what assets are protected. A legal platform that connects individuals with attorneys in multiple practice areas can help you evaluate your options without obligation. For example, CarInjuryAccident connects people with seasoned attorneys in personal injury, bankruptcy, DUI, social security and disability, and divorce, offering guidance for those facing serious legal and financial challenges.
Work With Professionals Before You File
Preparing financially for divorce is not a do-it-yourself project. You need a team that understands family law, tax, and financial planning. A family law attorney can explain your rights, help you gather evidence, and negotiate a settlement that protects your interests. A certified divorce financial analyst or a fee-only financial planner can model different scenarios and help you avoid costly mistakes. A tax professional can ensure that your settlement does not create an unexpected bill.
If you are unsure where to find qualified professionals, a legal resources platform like FormsByLawyers can connect you with attorneys who practice in your area. FormsByLawyers is not a law firm and does not provide legal advice, but it offers a patented attorney selection process that identifies the top five percent of attorneys annually based on peer influence and research. Users can request a free, no-obligation case review and receive quick quotes or customized quotes tailored to their situation. For individuals navigating divorce, bankruptcy, or other legal challenges, this kind of connection can make it easier to find representation without upfront cost.
When you meet with your attorney, bring your financial inventory, a list of questions, and a clear sense of your goals. Ask about temporary support, restraining orders, discovery procedures, and the timeline for your case. The more prepared you are, the more efficiently your attorney can work, and the more control you have over the outcome.
Protect Your Credit and Avoid Financial Missteps
Divorce can damage your credit if you are not careful. Joint debts remain the responsibility of both spouses until they are paid off or refinanced, even if the divorce decree assigns them to one person. If your ex-spouse misses a payment, the creditor can still come after you, and the late payment will appear on your credit report. To protect yourself, monitor your credit regularly, keep records of all payments, and work with your attorney to include clear language about debt responsibility in your settlement.
Avoid making major financial changes without legal guidance. Do not quit your job, hide assets, or transfer property in an attempt to influence the divorce. These actions can be seen as bad faith and may result in penalties, loss of credibility, or a less favorable settlement. Similarly, do not sign any documents, including settlement agreements or loan refinancing paperwork, without having your attorney review them first.
If you are facing a high-conflict divorce or suspect your spouse is hiding assets, consider hiring a forensic accountant. This professional can trace money, value businesses, and uncover hidden income. The cost may seem high, but the potential recovery often justifies the expense. Your attorney can help you decide whether a forensic accountant is necessary in your case.
Take the First Steps Today
Preparing financially before filing for divorce is about more than protecting your bank account. It is about giving yourself the information, resources, and professional support you need to make sound decisions during a stressful time. Start by gathering your financial documents, building an emergency fund, and understanding your state's property division rules. Then connect with an attorney who can guide you through the process and help you avoid mistakes that could cost you for years.
If you are ready to take the next step, consider requesting a free case review through a legal resource platform that connects you with qualified professionals in your area. With the right preparation and the right team, you can move through divorce with greater confidence and a clearer path toward financial stability.