Can You Sue for an Injury at a Friends House?
Injured at a friend's home? Understand your legal options and insurance claims. Call (833)-349-4659 for a free case review.
By Vesper Alden
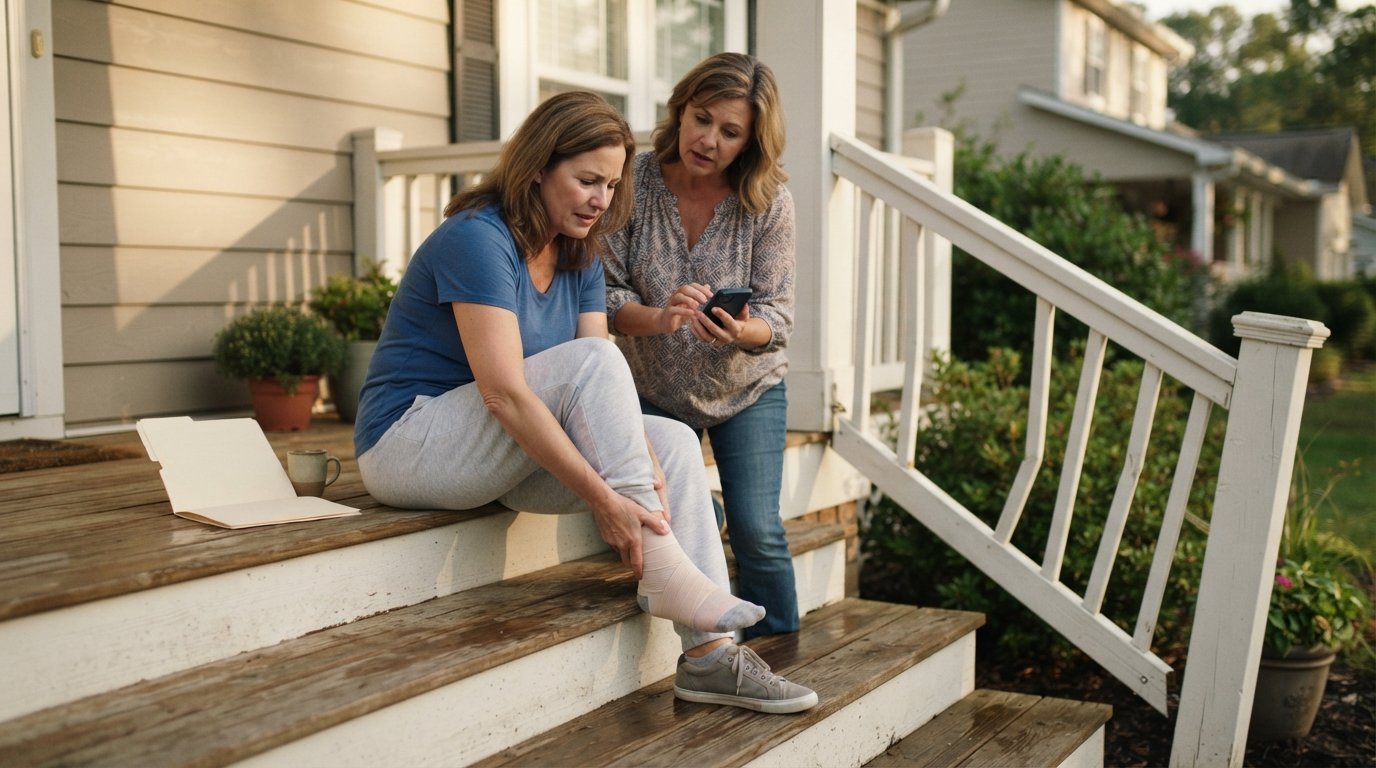
You slip on a wet kitchen floor during a backyard barbecue, or you trip over a loose stair rail at a holiday party. The pain is real, the medical bills are piling up, and the last thing you want is to damage a friendship. But you also deserve to recover. This guide answers the question: can you sue for an injury at a friends house? It explains how homeowners and renters insurance typically respond, the legal distinctions that affect your claim, and the practical steps to protect your health and your rights without turning a friendship upside down.
How Homeowners and Renters Insurance Handle Guest Injuries
Most homeowners and renters insurance policies include personal liability coverage. This coverage is designed to pay for injuries that guests suffer on the property, up to the policy limits. If you are injured at a friends house, the first source of compensation is usually that friend's homeowners or renters insurance, not the friend's personal bank account. The insurer will investigate the incident and may offer a settlement to cover medical expenses, lost wages, and pain and suffering. This is important because it means you can often recover damages without filing a lawsuit against your friend directly.
Liability coverage typically starts at $100,000 and can be higher depending on the policy. If your injuries are severe and exceed those limits, an umbrella policy might provide additional protection. However, if the homeowner is underinsured or the injury is catastrophic, a personal injury lawsuit might become necessary. It is also worth noting that renters insurance provides similar liability protection for tenants, so if your friend rents an apartment, their renters policy may respond in the same way.
One key point: insurance companies are not on your side. They may try to minimize your claim or deny liability. That is why documenting the scene and seeking medical attention immediately after the injury is critical. If you are unsure whether the homeowners policy will cover your injury, a free consultation with a personal injury attorney can clarify your options. You can also use a platform like LawyerOffer to connect with attorneys who handle premises liability cases.
Social Guest Versus Invitee and Licensee: Why Your Legal Status Matters
The legal duty a property owner owes you depends on your status when you are injured. In most states, visitors are classified as either invitees, licensees, or trespassers. Understanding these distinctions helps you determine whether your friend acted negligently and whether you have a viable claim.
An invitee is someone who enters the property for the owner's benefit, such as a customer in a store. A social guest at a friends house is typically considered a licensee, not an invitee. This means the homeowner must warn you of known dangers that you are unlikely to discover, but they do not have the same heightened duty to inspect for hidden hazards as they would for a business invitee. However, if the homeowner created the hazard (like leaving a slippery floor without warning) or knew about it and failed to fix it, they may still be liable.
Some states have abolished these distinctions and apply a general negligence standard. Under that standard, the homeowner owes a reasonable duty of care to all lawful visitors. Regardless of the label, the core question is whether the homeowner acted reasonably to prevent foreseeable harm. For example, if your friend knew the deck railing was loose and did not repair it or warn you, that could constitute negligence. The following list summarizes the key differences:
- Invitee: Enters for mutual benefit; owner owes highest duty to inspect and warn.
- Licensee (social guest): Enters for social purposes; owner must warn of known dangers but has no duty to inspect for hidden defects.
- Trespasser: Enters without permission; owner owes minimal duty, mainly to avoid willful harm.
Because social guests are usually licensees, you may need to show that your friend knew about the dangerous condition and failed to address it. This is why evidence of prior complaints or visible hazards is so valuable. If you can prove the homeowner was aware of the risk, your claim becomes much stronger.
The Risks to Your Friendship and How Claims Are Usually Handled
Suing a friend can feel like a betrayal, but it is important to understand that most injury claims at a friends house are resolved through the friend's insurance company, not through a direct lawsuit against the friend. The insurance company is contractually obligated to defend and indemnify the homeowner. In practice, you file a claim with the insurer, and the insurer negotiates a settlement. Your friend may never have to pay out of pocket, and the friendship can be preserved.
Still, the emotional strain is real. Many people hesitate to pursue a claim because they fear it will ruin the relationship. Open communication can help. Explain that you are not trying to punish them but need help covering medical bills. In many cases, friends are relieved that their insurance will handle it. However, if the insurer denies the claim or the friendship becomes strained, a lawsuit may be the only way to recover fair compensation.
It is also worth considering that a lawsuit might be necessary to compel the insurance company to pay a fair amount. Insurance companies often make low initial offers, and filing a lawsuit can pressure them to negotiate seriously. But litigation can be time-consuming and expensive. An attorney can help you weigh the pros and cons and decide whether a lawsuit is worth the personal cost.
Documenting the Scene and Medical Treatment Early
If you are injured at a friends house, your first priority should be your health. Seek medical attention immediately, even if you think the injury is minor. Some injuries, like concussions or internal bleeding, do not show symptoms right away. A medical record also creates a official link between the accident and your injuries, which is crucial for any insurance claim or lawsuit.
After you have seen a doctor, document the scene as soon as possible. Take photographs of the hazard that caused your injury, such as a broken step, a wet floor, or a loose rug. If you cannot return to the scene, ask your friend to take photos or preserve any evidence. Write down what happened while your memory is fresh, including the time, location, and any warnings you received (or did not receive).
Collect contact information for any witnesses. If your friend has homeowners insurance, report the incident to them in writing. Keep copies of all medical bills, receipts, and correspondence. This documentation will be essential when you file a claim. The following steps can help you build a strong case:
- Seek medical treatment and follow your doctor's advice.
- Photograph the hazard and the surrounding area.
- Write a detailed account of the incident.
- Obtain witness names and contact details.
- Notify the homeowner's insurance company promptly.
Even if you are unsure about suing, having this evidence ready will protect your rights. Insurance companies are more likely to take your claim seriously when you present organized documentation.
Whether a Consultation Makes Sense for Smaller Injuries
Not every injury at a friends house warrants a lawsuit. If your injuries are minor and medical bills are low, you may be able to resolve the matter directly with the insurance company. However, even for smaller injuries, a consultation with a personal injury attorney can be valuable. Many attorneys offer free initial consultations, and they can tell you whether you have a viable claim and what it might be worth.
For smaller injuries, the cost of litigation might outweigh the potential recovery. But an attorney can often negotiate a settlement with the insurer without filing a lawsuit, saving you time and stress. Additionally, some states have statutes of limitations that limit how long you have to file a claim. A consultation ensures you do not miss any deadlines.
If you are unsure whether to pursue a claim, consider the following factors:
- The severity of your injuries and the amount of medical expenses.
- Whether the homeowner's insurance policy has adequate coverage.
- The strength of evidence showing the homeowner's negligence.
- Your willingness to potentially strain the friendship.
An attorney can help you evaluate these factors objectively. If you decide not to pursue a claim, you should still document everything in case your injuries worsen or new evidence emerges.
Steps to Take If You Decide to Sue
If you determine that a lawsuit is necessary, the process begins with filing a complaint in court. You will need to prove that the homeowner breached their duty of care and that their breach caused your injuries. An attorney can help you gather evidence, interview witnesses, and present your case. Most personal injury lawsuits settle before trial, but having an attorney by your side increases your chances of a fair outcome.
Before filing a lawsuit, you may be required to send a demand letter to the homeowner's insurance company. This letter outlines your injuries, the facts of the incident, and the amount you are seeking. The insurer may respond with a settlement offer. If negotiations fail, you can proceed with litigation. Keep in mind that lawsuits against friends can be emotionally taxing, so consider mediation as an alternative dispute resolution method.
Finally, remember that the law is on your side if the homeowner was negligent. You are not being disloyal by seeking compensation for injuries you did not cause. A reputable attorney can help you navigate the process with sensitivity and professionalism.
For those who prefer to explore their options without an upfront commitment, FormsByLawyers offers a free case review and connects you with attorneys from its network. However, note that FormsByLawyers is not a law firm and does not provide legal advice. It simply connects you with legal professionals who can evaluate your situation.
Injury at a friends house can be a delicate situation, but you have legal rights. Whether you pursue an insurance claim or a lawsuit, taking prompt action and seeking professional guidance can help you recover the compensation you deserve while minimizing the impact on your friendship.